Income documents
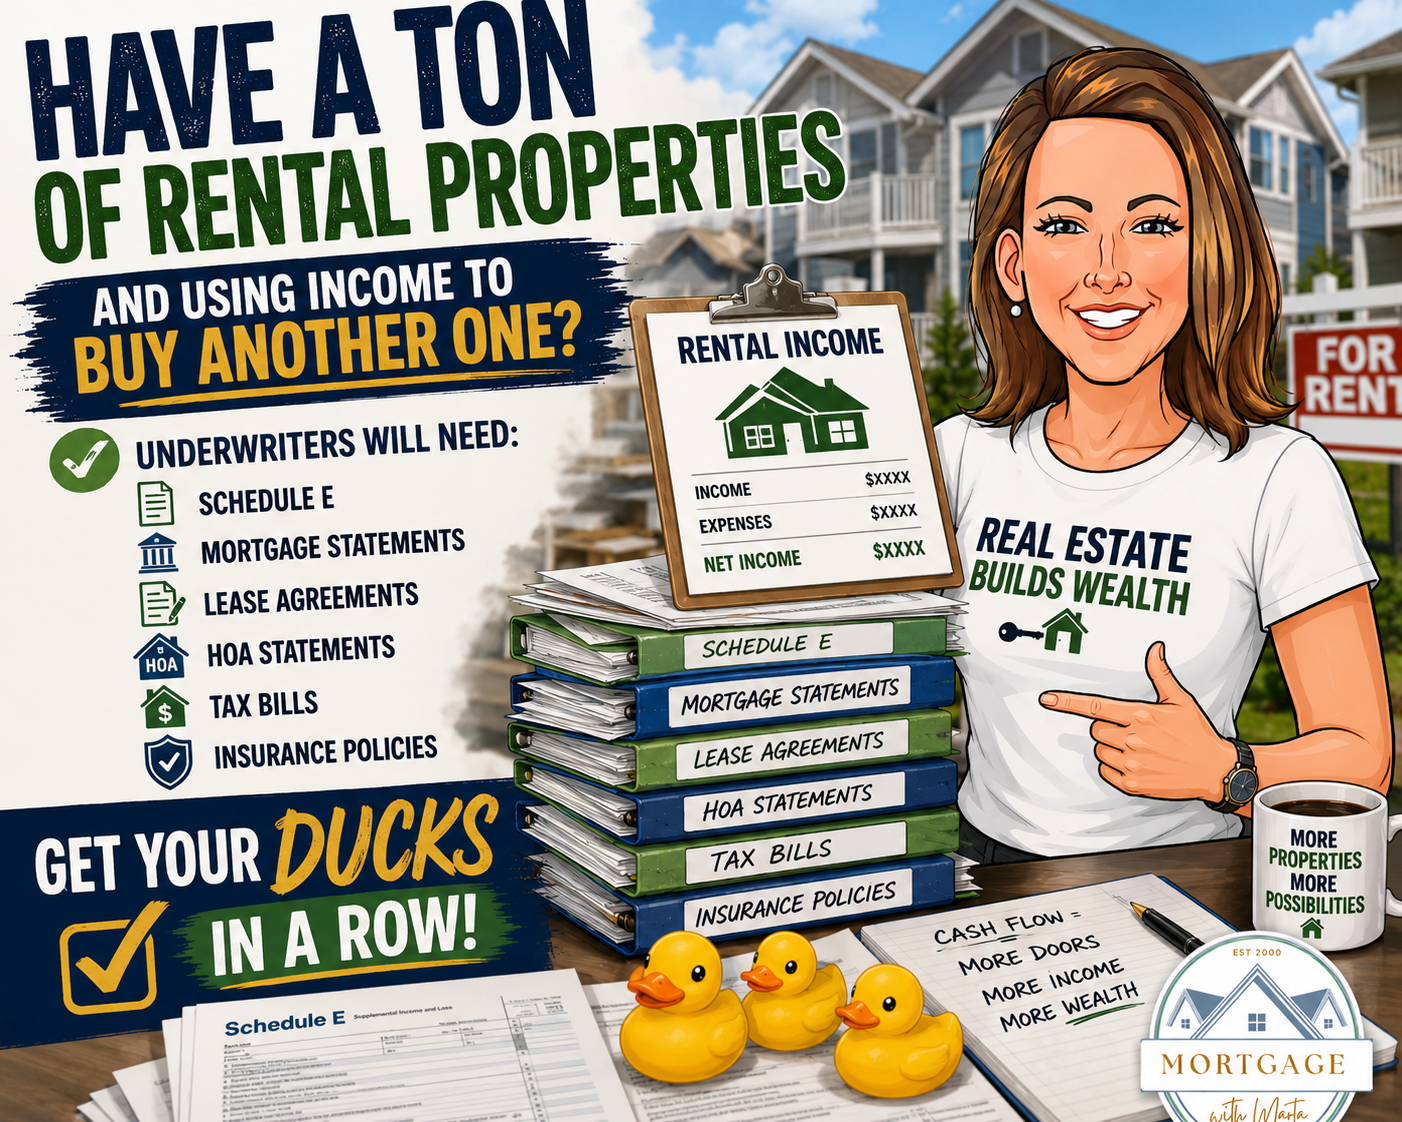
Underwriting may request Schedule E, complete tax returns, current leases, and evidence of deposits or market rent, depending on the property history and program.
Property expenses
Gather mortgage statements, tax bills, insurance policies, and HOA statements for each financed property.
Vacancy and calculation rules
A lender may apply a vacancy factor and account for principal, interest, taxes, insurance, HOA dues, and other expenses. A signed lease is not always the final usable-income number.
Get your ducks in a row
Organize each property's documents separately before applying. Your underwriter and your stress level will both appreciate it.
Your next step
Let’s talk about what this means for you.
You do not have to figure out every mortgage detail on your own. Tell me the goal and we can work through the questions.
Ask Marta a question