Fixed-rate mortgage
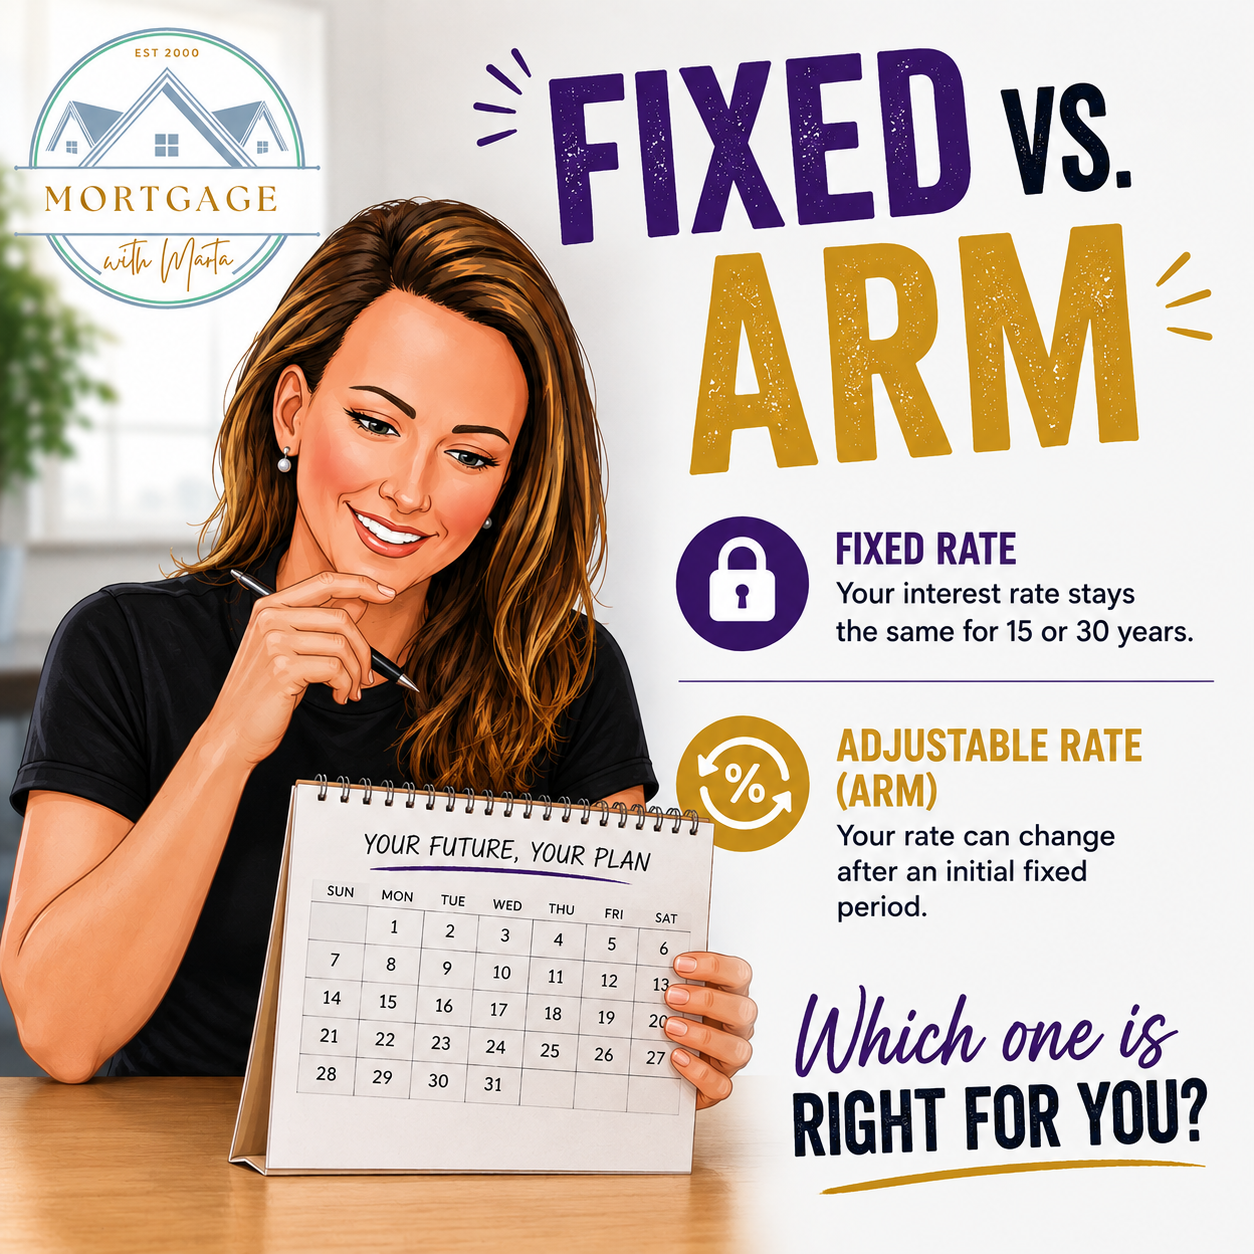
A fixed-rate mortgage keeps the interest rate the same for the full loan term. It offers predictable principal and interest payments and can make sense when you plan to keep the home or value long-term stability.
Adjustable-rate mortgage
An adjustable-rate mortgage starts with a fixed period, then the rate may change based on the loan’s index, margin, adjustment schedule, and caps. The initial rate may be lower, but future payments can increase.
When an ARM may make sense
An ARM may be worth comparing if you reasonably expect to sell, move, refinance, or pay off the loan before the adjustable period begins. That plan should still include a backup if life or market conditions change.
Your timeline decides the strategy
Do not automatically assume fixed is always better or that the lowest starting rate wins. Compare the fixed period, adjustment caps, worst-case payment, costs, break-even point, and your actual timeline.
Your next step
Let’s talk about what this means for you.
You do not have to figure out every mortgage detail on your own. Tell me the goal and we can work through the questions.
Ask Marta a question