As little as 3.5% down
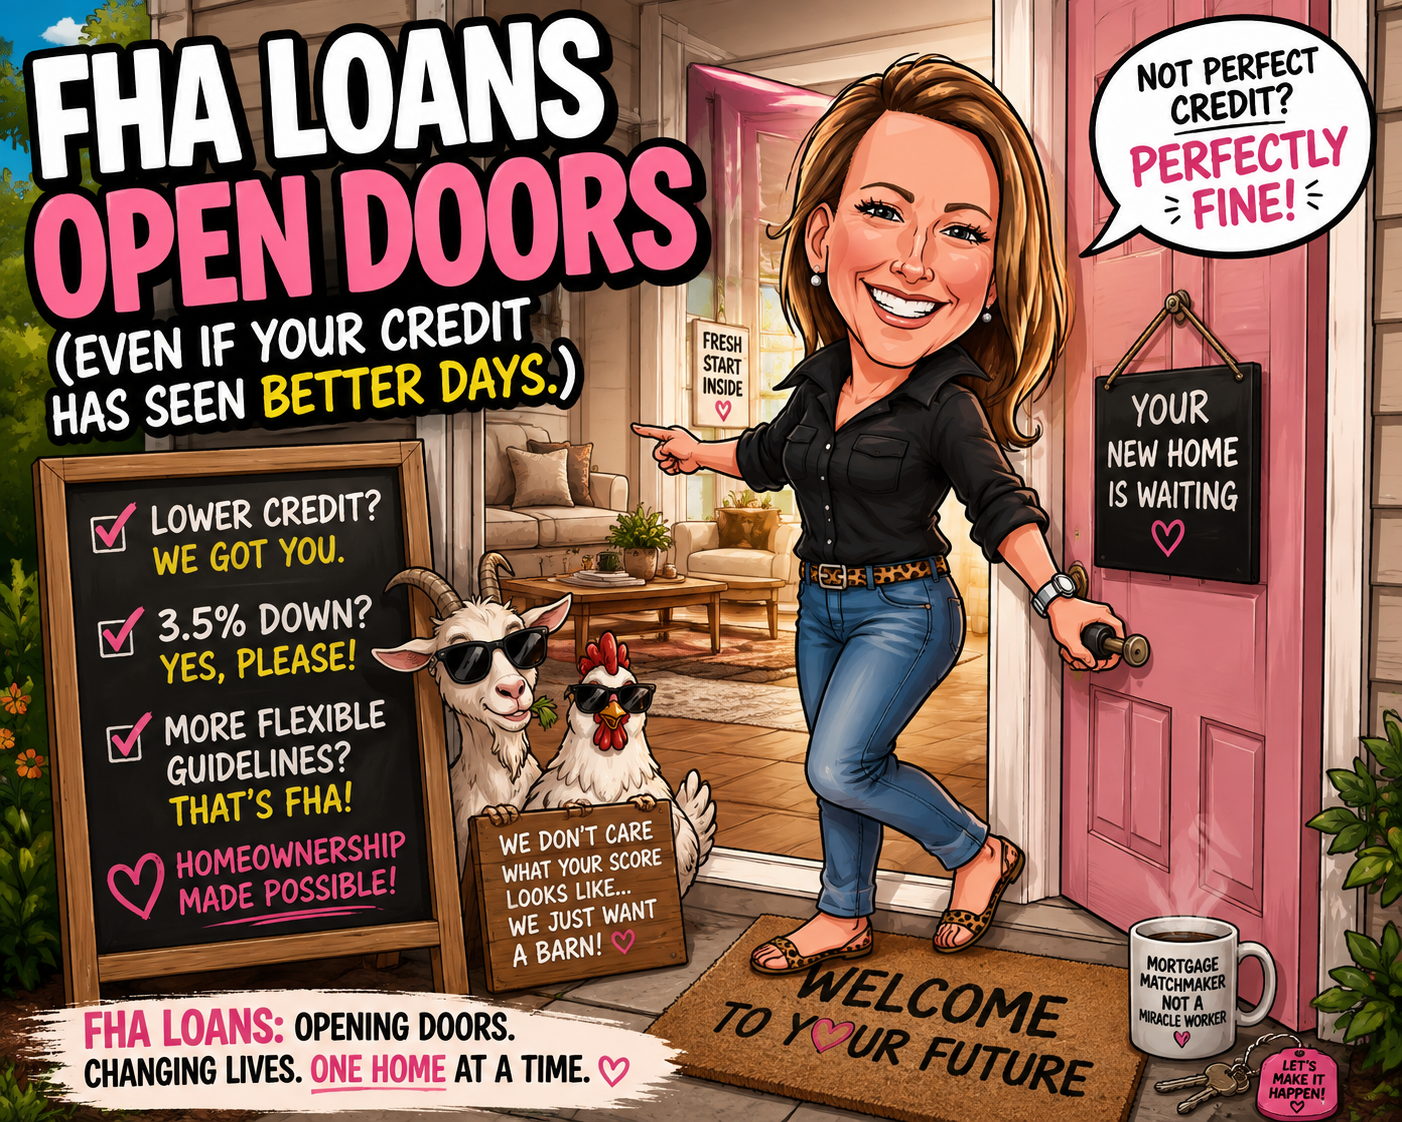
Eligible borrowers may purchase with a down payment as low as 3.5%. The down payment and allowable closing funds may come from approved sources, including eligible gifts and assistance programs.
Flexible credit guidelines
FHA financing can be more forgiving of past credit challenges than some conventional options. The full credit profile, payment history, score, and automated or manual underwriting result still matter.
Room for a higher DTI
FHA may allow a higher debt-to-income ratio when the overall file has strong compensating factors and receives an acceptable underwriting result. A higher allowed ratio does not mean the payment is automatically comfortable for your budget.
Know the mortgage insurance
FHA loans generally include an upfront mortgage insurance premium and an annual premium collected monthly. The best comparison includes the total payment, cash to close, and long-term cost, not only the interest rate.
Compare before you choose
FHA can be a great fit, but it is not automatically the best fit. I compare FHA, conventional, VA, and other eligible options to find the loan that supports your goals, payment, cash, and property.
Your next step
Let’s talk about what this means for you.
You do not have to figure out every mortgage detail on your own. Tell me the goal and we can work through the questions.
Ask Marta a question