The basic formula
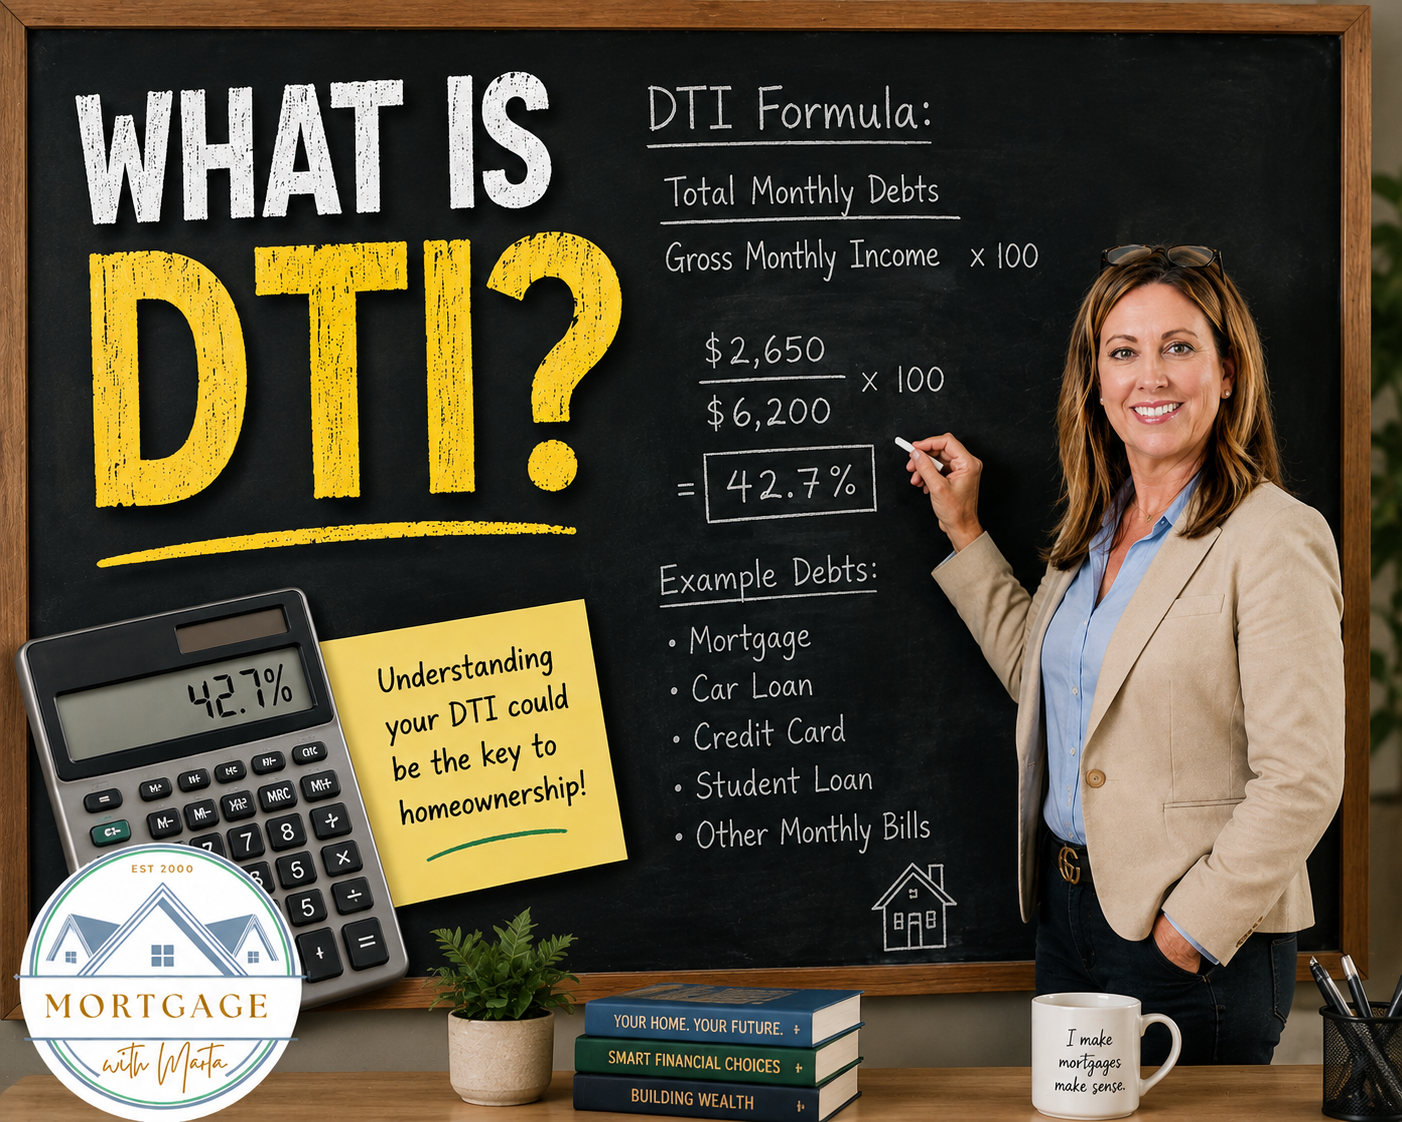
Divide the applicable monthly debts by qualifying gross monthly income, then multiply by 100. For example, $2,650 divided by $6,200 equals about 42.7%.
Debts commonly included
The proposed housing payment, car loans, credit cards, student loans, support obligations, and other recurring debts may count under program rules.
Not every bill is DTI debt
Utilities, groceries, phone bills, and other living expenses are generally not entered into the formal DTI calculation, although they still matter to your real budget.
Higher does not mean hopeless
Program, credit, reserves, down payment, residual income, and automated underwriting results can change what is possible. Comfortable payment still matters more than maximum approval.
Your next step
Let’s talk about what this means for you.
You do not have to figure out every mortgage detail on your own. Tell me the goal and we can work through the questions.
Ask Marta a question